All Risks and Why You Need it
What are all risks. Quite simply it is items that are removed from your premises and travel with you. They are covered world wide and the cover is much wider than contents.
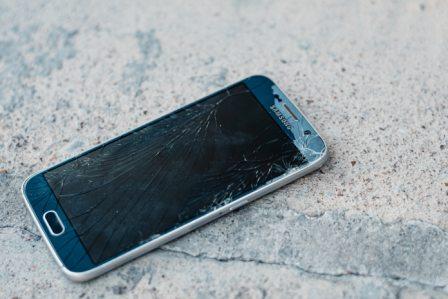
These items range from electronic equipment, cell phones, laptops and portable electronic equipment to Gym bags, hand bags, spectacles / sunglasses and jewellery.
A lot of clients do not think about all their daily items that may leave the home such as hearing aids or even medication and machines for Diabetes.
The general idea of insurance is to cover you for a loss that could cripple you financially. With this in mind, insuring a few items that are not worth much separately does not make sense when you consider the premiums charged and the amount you would be paid out. However a wedding ring could be thousands of Rands and if it went missing or was stolen, it could take years to make the money back to replace this yourself.
This section is also incredibly helpful when going on holiday. Think about how we pack a car with our clothes, cameras and items to keep the kids busy. Insurers do not expect every item to be specified so they do allow for this to be grouped under Unspecified All Risks which gives a total limit and a limit per item. You would have to check with your insurer or broker which items must be specified on their own and which can be grouped.
All risks is a wide section allowing you to cover a wide variety of items that are out of the ordinary especially when it comes to our hobbies. Photographic equipment, Drones or even your more special hobbies like para-gliding or camping equipment can be covered under All Risks.
Tips and What to Note
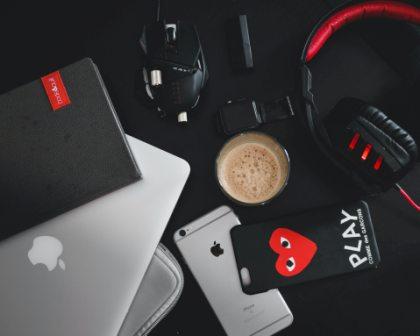
When claiming for All Risks items, insurers will ask for some form of proof of ownership. We recommend always keeping a photo of the item and its box as well as any serial numbers. Keeping the physical box or purchase invoice would be preferential however a photo backup is always practice.
Precious metal prices have risen dramatically over the last few years and just looking at gold in the last year has increased by 30%. We always advise clients to update their valuation certificates even if just on renewal to make sure you are insured for the correct value.
Always make sure you have serial numbers or cell phone IMEI numbers listed on the policy. This will tell the insurers which item it is that was lost,stolen or damaged.
It is up to the insurer if they want to repair, replace or payout for the items. So do not always expect to be paid out in cash for items just to get new ones. Wait for your insurance to say what they will be doing before going out and replacing the item yourself.
If an item is damaged, the insurers may ask for a damage report which states the cause of the damage. These can cost a few hundred rand to obtain. Keep these invoices as you can submit them for payment with you claims.
We can see that is quite important to cover your items when they leave the premises and can be helpful when it is not economically viable for you to pay these claims out your own pocket. So decide what you want to cover and what you can afford in premium vs the risk to the damage of the item.